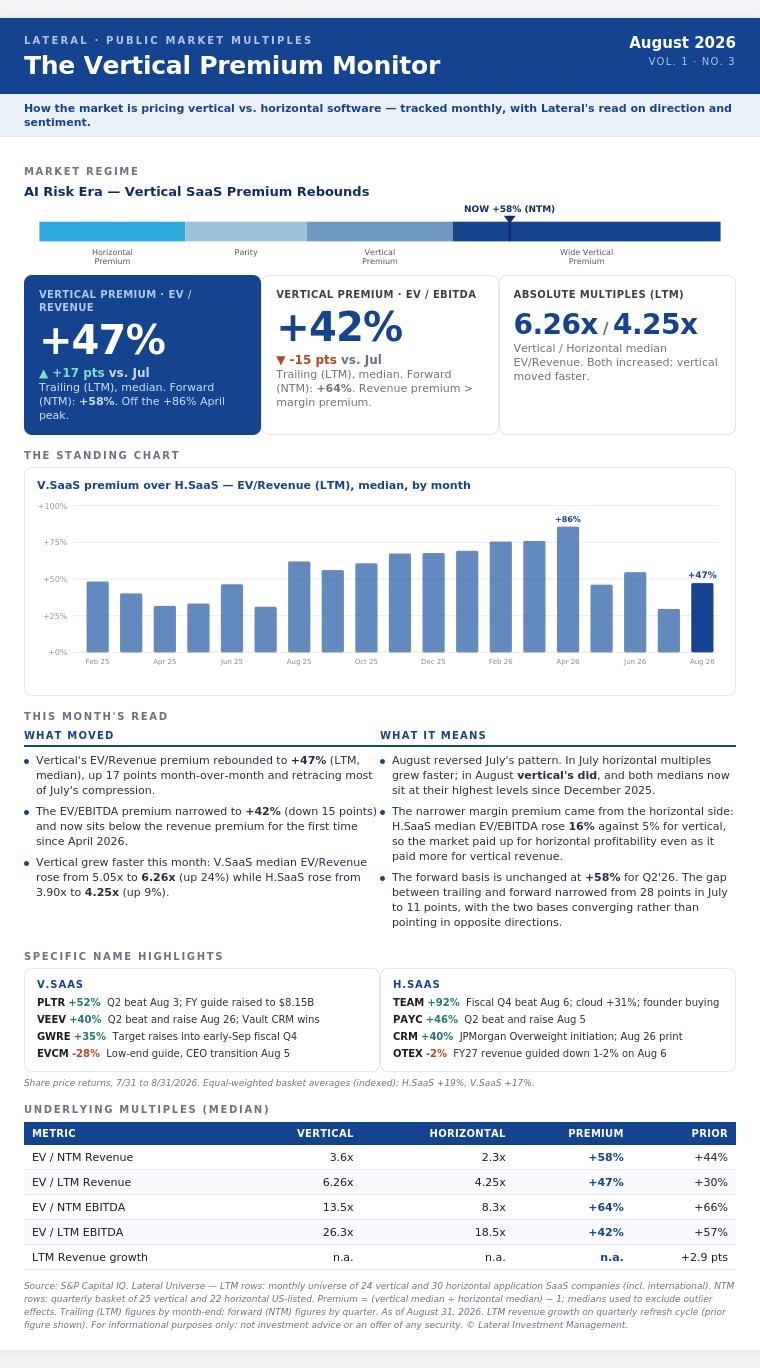
The vertical software premium over horizontal software rebounded in August. The EV/Revenue premium rose to +47% (LTM, median), up 17 percentage points versus July, while the EV/EBITDA premium narrowed to +42%, down 15 points. On a forward (NTM) basis the revenue premium stands at +58% for Q2'26, unchanged from last month's print.
The pattern was the reverse of July when horizontal software multiples grew faster and narrowed the vertical over horizontal premium. This month, the vertical software basket led the appreciation in valuation multiples but horizontal multiples also increased. Both vertical and horizontal software median multiples are now trading at their highest levels since December 2025.
What moved
- Vertical software's EV/Revenue premium rebounded to +47% (LTM, median), up 17 points month-over-month and retracing most of July's compression. The series remains below the +86% April peak.
- The EV/EBITDA premium narrowed to +42% (down 15 points) and now sits below the revenue premium for the first time since April 2026.
- Vertical software multiples grew faster: Vertical SaaS median EV/Revenue rose from 5.05x to 6.26x while Horizontal SaaS rose from 3.90x to 4.25x.
What it means
- The wider revenue premium reflects a faster vertical move rather than a horizontal decline. Both baskets rose in absolute terms for the second consecutive month.
- The narrower EBITDA premium came from the horizontal side: Horizontal SaaS median EV/EBITDA rose 16% against 5% for vertical, so the market paid up for horizontal software profitability even as it paid more for vertical revenue.
- The gap between trailing and forward narrowed from 28 points in July to 11 points. The two bases converged this month rather than pointing in opposite directions.
Specific name highlights
- Positive news drove stock market appreciation. In the vertical software basket defense tech vendor Palantir rose 52% (Q2 report on August 3: revenue of $1.94 billion against $1.81 billion expected, full-year guidance raised to $8.15 billion), life sciences vendor Veeva rose 40% (August 26: revenue of $928 million, up 17.6%, with guidance raised), and Guidewire rose 35% ahead of its September report.
- The horizontal sosftware basket was led by development tools vendor Atlassian, up 92% (August 6 report: fiscal Q4 revenue of $1.77 billion with cloud revenue up 31%, plus a $250 million founder purchase pledge), payroll vendor Paycom, up 46% on an August 5 beat and raise, and Salesforce, up 40% into and through its August 26 fiscal Q2 report after JPMorgan initiated coverage at Overweight with a $265 Dec 2027 price target.
- Underperformance was mostly idiosyncratic to specific stocks. EverCommerce fell 28% after its August 5 report with weak growth and guidance and a CEO transition. Content management company OpenText slipped 2% as an August 6 profit beat came with fiscal 2027 revenue guidance down. Trade and logistics software vendor WiseTech's had a strong month but the trailing multiple compressed 15% on e2open consolidation .
The Vertical Premium Monitor — August 2026. Source: S&P Capital IQ; Lateral analysis; company reports. As of August 31, 2026.